Farmers & farm families · North Mayo
Pass on the farm, not a tax bill.
For many families in Crossmolina, Ballina and north Mayo, the farm is a home, a history and a hard-earned legacy. With land values climbing, the tax on a farm transfer can be enough to put its future at risk. Planned properly, it is usually nothing at all.
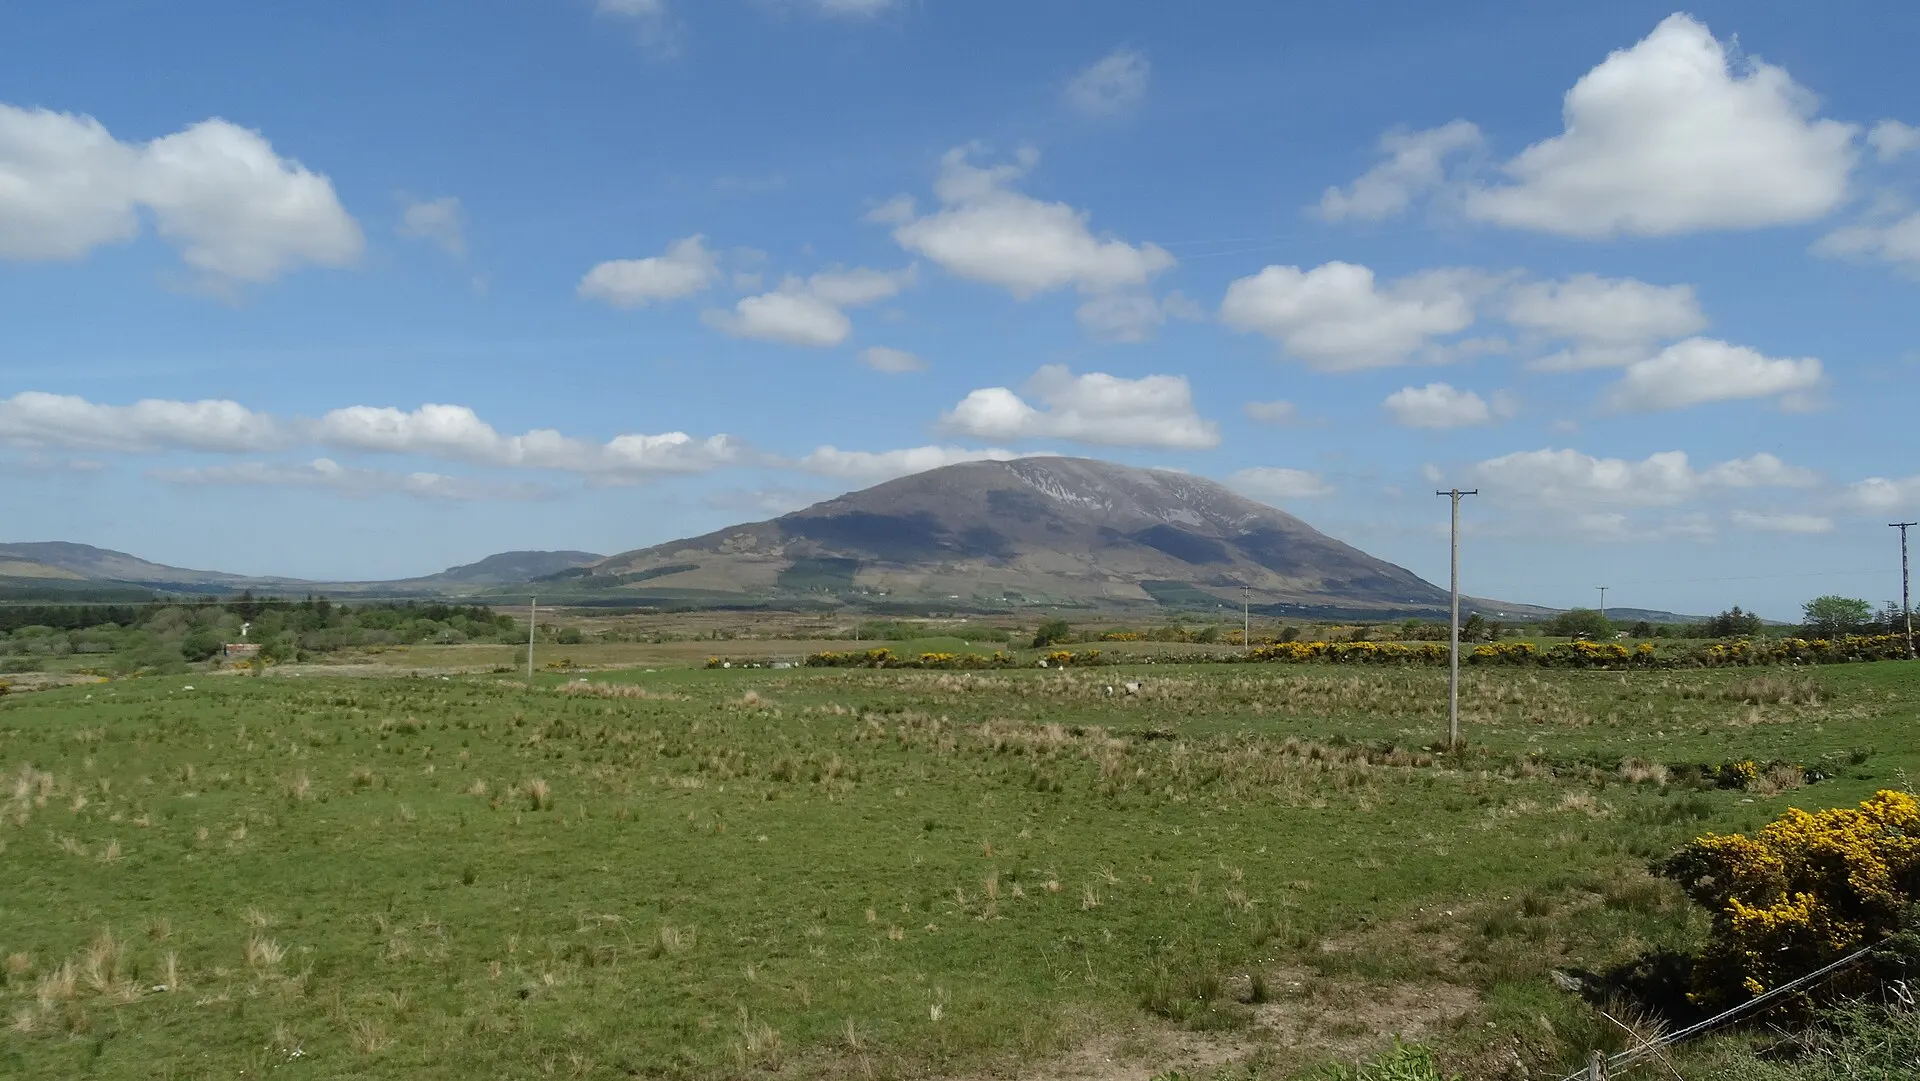
Glen Nephin, Co. Mayo. Photo: Colin Park, CC BY-SA 2.0

The 90% rule
What Agricultural Relief does to the numbers.
Agricultural Relief lets a successor reduce the taxable value of qualifying farm property by 90%. Combined with the tax-free threshold for children, the result for a typical Mayo farm looks like this.
Step 1
€1,200,000
Market value of the farm being gifted
Step 2
€120,000
Taxable value after 90% Agricultural Relief
Step 3
€0
Typical tax bill once the €400,000 child threshold is applied
Without the relief, the same transfer could cost the family over €300,000. The relief is not automatic: it depends on tests that look at the six years before and after the transfer.
60-second check
Would your transfer qualify?
Four questions covering the conditions that most often catch Mayo families out. Nothing is stored or sent anywhere.
The common Mayo trap
A son or daughter with a high-value home in Dublin, or significant off-farm savings, may fail the 80% test. If the threshold is at risk, there are legitimate ways to rebalance, but only before the papers are signed.
Answer all four questions to see where you stand.
A guide only, not tax advice. Agricultural Relief depends on your full circumstances and on Revenue rules at the date of the transfer.
The full picture
Agricultural Relief is the big one. It is not the only one.
A good succession plan is a multi-year strategy that uses each relief where it fits.
Retirement Relief
You don't have to retire to claim it. From age 55, with 10 years of ownership and use, it can reduce Capital Gains Tax on a transfer to zero. Limits apply: €10 million for transfers to children aged 55 to 69, and €3 million from age 70.
Consanguinity Relief
Reduces Stamp Duty from 7.5% to 1% on transfers between relatives.
Young Trained Farmer Relief
A full 0% Stamp Duty exemption for successors under 35 with a Green Cert.
Business Relief
For the non-agricultural assets that often sit alongside a farm, such as a farm shop or a separate commercial yard.
The €3,000 small gift exemption
Succession is rarely a single transaction. Annual gifting, used steadily over years, moves value to the next generation outside the tax net.
Grant available
€1,500 towards your advice
The Department of Agriculture's Succession Planning Advice Grant helps farmers over 60 cover professional accounting and legal costs. We are registered to help you claim it while we build your plan.
Questions we hear most
Straight answers.
Does Agricultural Relief apply to the farmhouse?
Yes, provided the house is of a character appropriate to the property. A mansion on 5 acres usually won't qualify, but a standard farmhouse on a working 80-acre Mayo farm will.
What happens if the land is sold within 6 years?
This is called clawback. If the successor sells the land or stops farming it within the six-year window, Revenue will demand the 90% relief back, with interest.
Can a niece or nephew qualify?
Yes. Under the favourite niece or nephew rules they can be treated as a child for the tax-free threshold if they have worked on the farm for a set amount of time.
Why local advice matters
National firms don't know the difference between a farm in Meath and a farm in the shadow of Nephin.
We understand north Mayo land values, the Ballina Mart prices and the family dynamics that make Mayo farming unique. We also prepare farm accounts year in, year out, so your succession plan is built on numbers we already know.
Further reading
John's guides for Mayo farmers.
8 March 2026
Agricultural Relief Ireland 2026: The Essential Guide for Mayo Farmers
Read the article →
11 April 2026
Navigating Retirement Relief: A Vital Guide for Irish Farmers and Business Owners
Read the article →
24 March 2026
Strategic Succession Planning in Mayo: The €3,000 Exemption
Read the article →